Check price and discounts
Compare realised prices, rebates and contract terms. Separate a deliberate investment in a new account from discounting that no longer earns an acceptable contribution.
Example solution · Commercial performance
Sales are up, but the contribution left after direct costs has barely moved. A channel view helps a commercial team see where to investigate before committing to more growth.
Illustrative example. All data is fictional. This demonstration shows an analytical approach, not a client engagement or an achieved result.
Imagine a workplace-supplies distributor reviewing two comparable, complete quarters. Business contracts are growing quickly, the web channel is expanding, and total revenue looks healthy. The commercial lead wants to know: is that extra revenue making the business more valuable?
A sales-only report cannot answer that. This example puts net revenue and contribution alongside each other, using the same channel definitions and cost treatment in both quarters. It gives finance and sales a shared starting point for the discussion.
Fictional report · Quarter B versus Quarter A
A$2.30m → A$2.60m
A$775.0k → A$784.1k
33.70% → 30.16%
On smaller screens, scroll the table sideways to compare all measures. Amounts below are A$000; pp means percentage points.
| Channel | Net revenue | Revenue change | Contribution | Prior rate | Current rate |
|---|---|---|---|---|---|
| Business contracts | 1,080 | +20.0% | 237.6 | 30.0% | 22.0% |
| Direct web | 510 | +27.5% | 193.8 | 40.0% | 38.0% |
| Trade partners | 680 | −2.9% | 210.8 | 30.0% | 31.0% |
| Service agreements | 330 | +10.0% | 141.9 | 45.0% | 43.0% |
| Total | 2,600 | +13.0% | 784.1 | 33.70% | 30.16% |
Revenue rose 20%, but the contribution rate fell from 30% to 22%. That channel now contributes A$32.4k less than in the prior quarter, despite selling more. The highlighted row identifies the first area to investigate.
Definition: contribution is net revenue less product, fulfilment and directly attributable service costs. It excludes corporate overheads and is not net profit. Rates use unrounded figures; displayed changes are rounded.
The report identifies where performance changed. It does not establish why the margin fell. The next step is to test the possible drivers with the people who own the pricing, product and cost information.
Compare realised prices, rebates and contract terms. Separate a deliberate investment in a new account from discounting that no longer earns an acceptable contribution.
Look at which products and customers account for the extra sales. Test whether growth has shifted towards lower-margin items or more expensive service requirements.
Review delivery frequency, order sizes, returns and direct support costs where data is available. Agree which costs can reasonably be attributed to each channel.
A hypothetical improvement from 22% to 27% contribution on unchanged business-contract revenue would add A$54,000 per quarter: A$1,080,000 × 5 percentage points.
This is a sensitivity calculation, not achieved savings or a forecast. It assumes revenue and all other factors remain unchanged; a real pricing or service change could affect demand and costs.
This approach may suit a distributor, retailer or consumer brand whose sales, rebates and cost reports tell different parts of the story. It is particularly useful when teams can see growth but struggle to explain what it contributes.
A scoped engagement could bring together an agreed revenue and cost view, documented measure definitions, a channel or customer comparison, and a prioritised set of questions for the decision meeting. A recurring dashboard can be scoped separately through Power BI consulting.
For an initial conversation, describe the decision you need to make, who uses the report and which data sources you have. An outline is enough; we can agree how to review sample data once we understand the scope.
For a different reporting question, explore the budget and forecast control example.
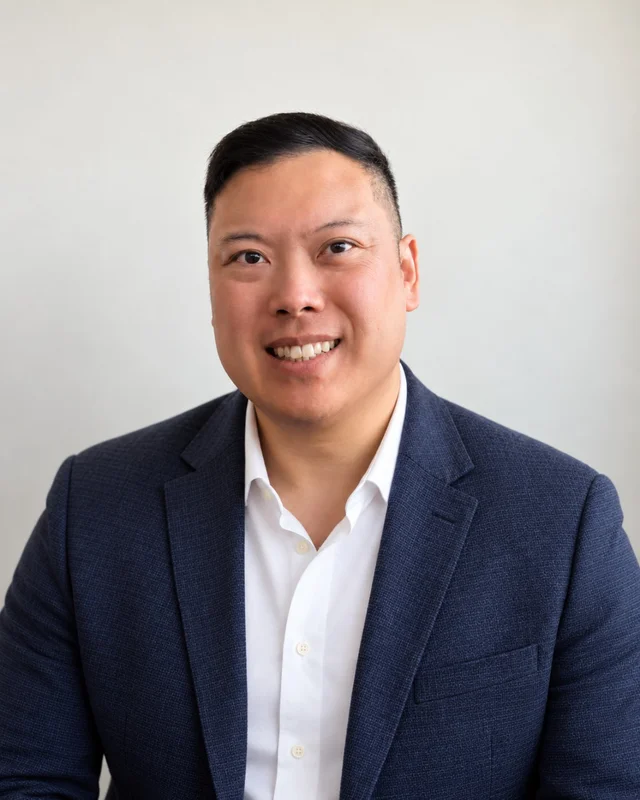
Your partner in the work
Sam is the Founder & Principal Consultant of Stratlens. He combines strategy, analytics and consulting experience with hands-on Power BI, SQL and Excel work.
Discuss the business question first, then agree the data, deliverables, timing and fee. Consulting is available remotely worldwide.
Meet Sam and explore Data & InsightsTell Sam which part of your performance is difficult to explain. We can discuss whether a focused commercial review would help.
Discuss your margin question